Welcome 2026: Thinking About Selling Your Home This Year?Welcome to 2026! 🎉 A new year often brings fresh goals, big decisions, and for many homeowners, the question: “Is this the year I

Dated: June 17 2025
Views: 535
What Credit Score Do You Need to Buy a Home?
If you’re thinking about buying a home, one of the first things you’ll hear about is your credit score—and for good reason! Your credit score can play a big role in what type of loan you qualify for, how much you can borrow, and the interest rate you’ll pay. But how high does your score really need to be?
Let’s break it down:
Your credit score is a three-digit number (ranging from 300 to 850) that reflects your credit history. Lenders use it to evaluate how risky it might be to lend you money. The higher your score, the better your chances of getting approved for a mortgage—and locking in a better rate.
Here’s a general guide to the minimum credit scores typically needed for different types of home loans:
🔹 FHA Loan – Minimum Score: 580 (with 3.5% down)
FHA loans are government-backed and great for first-time homebuyers or buyers with less-than-perfect credit. Some lenders may allow scores as low as 500, but that usually requires at least a 10% down payment.
🔹 Conventional Loan – Minimum Score: 620
Conventional loans are not backed by the government and usually require a higher credit score. A better score also means better interest rates.
🔹 VA Loan – Recommended Score: 620 (varies by lender)
Available to eligible veterans and active-duty military. VA loans often offer great rates and no down payment. Credit requirements can vary slightly depending on the lender.
🔹 USDA Loan – Recommended Score: 640
These loans are for rural and suburban homebuyers who meet income limits. They typically require no down payment and are backed by the USDA.
While those are the minimums, the sweet spot for better rates is typically 740 or higher. But don’t worry if you’re not quite there! Many buyers are approved with scores in the 600s. Your down payment, debt-to-income ratio, and financial history also play a big role in loan approval.
Pay down credit card balances
Make on-time payments
Avoid taking on new debt
Check your credit report for errors
Limit hard inquiries on your credit
You don’t need perfect credit to buy a home—but the better your score, the more options you’ll have. If you're thinking about purchasing soon and aren’t sure where you stand, now is the time to check your credit and connect with a local lender for a free pre-approval or credit evaluation.
Need a trusted lender recommendation or want to talk through your options? I’d be happy to help you get started on the path to homeownership!
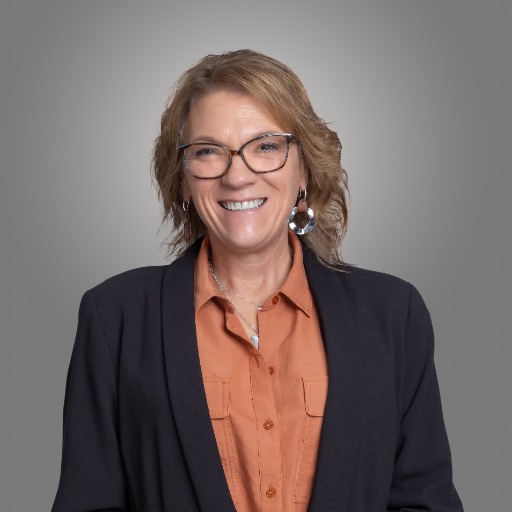
Rhonda Woolsey – Realtor® | Community-Focused, Family-DrivenHi, I’m Rhonda Woolsey, and I’ve been a Realtor® for 11 years. Before that, I spent 18 years in property managemen....
Welcome 2026: Thinking About Selling Your Home This Year?Welcome to 2026! 🎉 A new year often brings fresh goals, big decisions, and for many homeowners, the question: “Is this the year I
New Year, New Chapter: Get Your Home Ready to Sell This New Year’s EveAs the clock ticks down on New Year’s Eve, many of us are reflecting on the past year and setting intentions for a
🏡 Questions to Ask Yourself When Deciding Where to MoveChoosing where to live is one of the biggest decisions you’ll ever make — and it’s about so much more than just finding
Why an Open House Still Matters in Today’s MarketIn an age of online listings, virtual tours, and social media marketing, you may wonder—do open houses still work? The answer is a
 The information displayed on this page is confidential, proprietary, and copyrighted information of Heartland Multiple Listing Service, Inc. (
Heartland MLS
). Copyright 2026, Heartland Multiple Listing Service, Inc. Heartland MLS and Crown Realty do not make any warranty or representation concerning the timeliness or accuracy of the information displayed herein. In consideration for the receipt of the information on this page, the recipient agrees to use the information solely for the private noncommercial purpose of identifying a property in which the recipient has a good faith interest in acquiring. Data last updated on September 23, 2026 7:58 PM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
